Founder and CEO Bill Deng highlights the role of AI, human expertise and cross-border cooperation in making digital finance safer for SMEs.
XTransfer Founder and CEO Bill Deng has shared his perspectives on strengthening digital trust in cross-border commerce in a World Economic Forum article published on 23 October 2026. Featuring contributions from Deng and Noman Azhar, CEO of Zindigi-JS Bank, the article examines how technology can expand financial inclusion while helping prevent fraud.[weforum]
The discussion comes amid growing international attention to digital financial safety. On 14 October, during the 2026 IMF–World Bank Group Annual Meetings in Bangkok, the IMF and World Bank Group released the Bangkok Blueprint for Fraud-Resilient Financial Services, developed in coordination with the Bank of Thailand. The framework calls for coordinated action across the financial sector and wider digital ecosystem to address cyber-enabled fraud.[imf][thailand.prd.go]
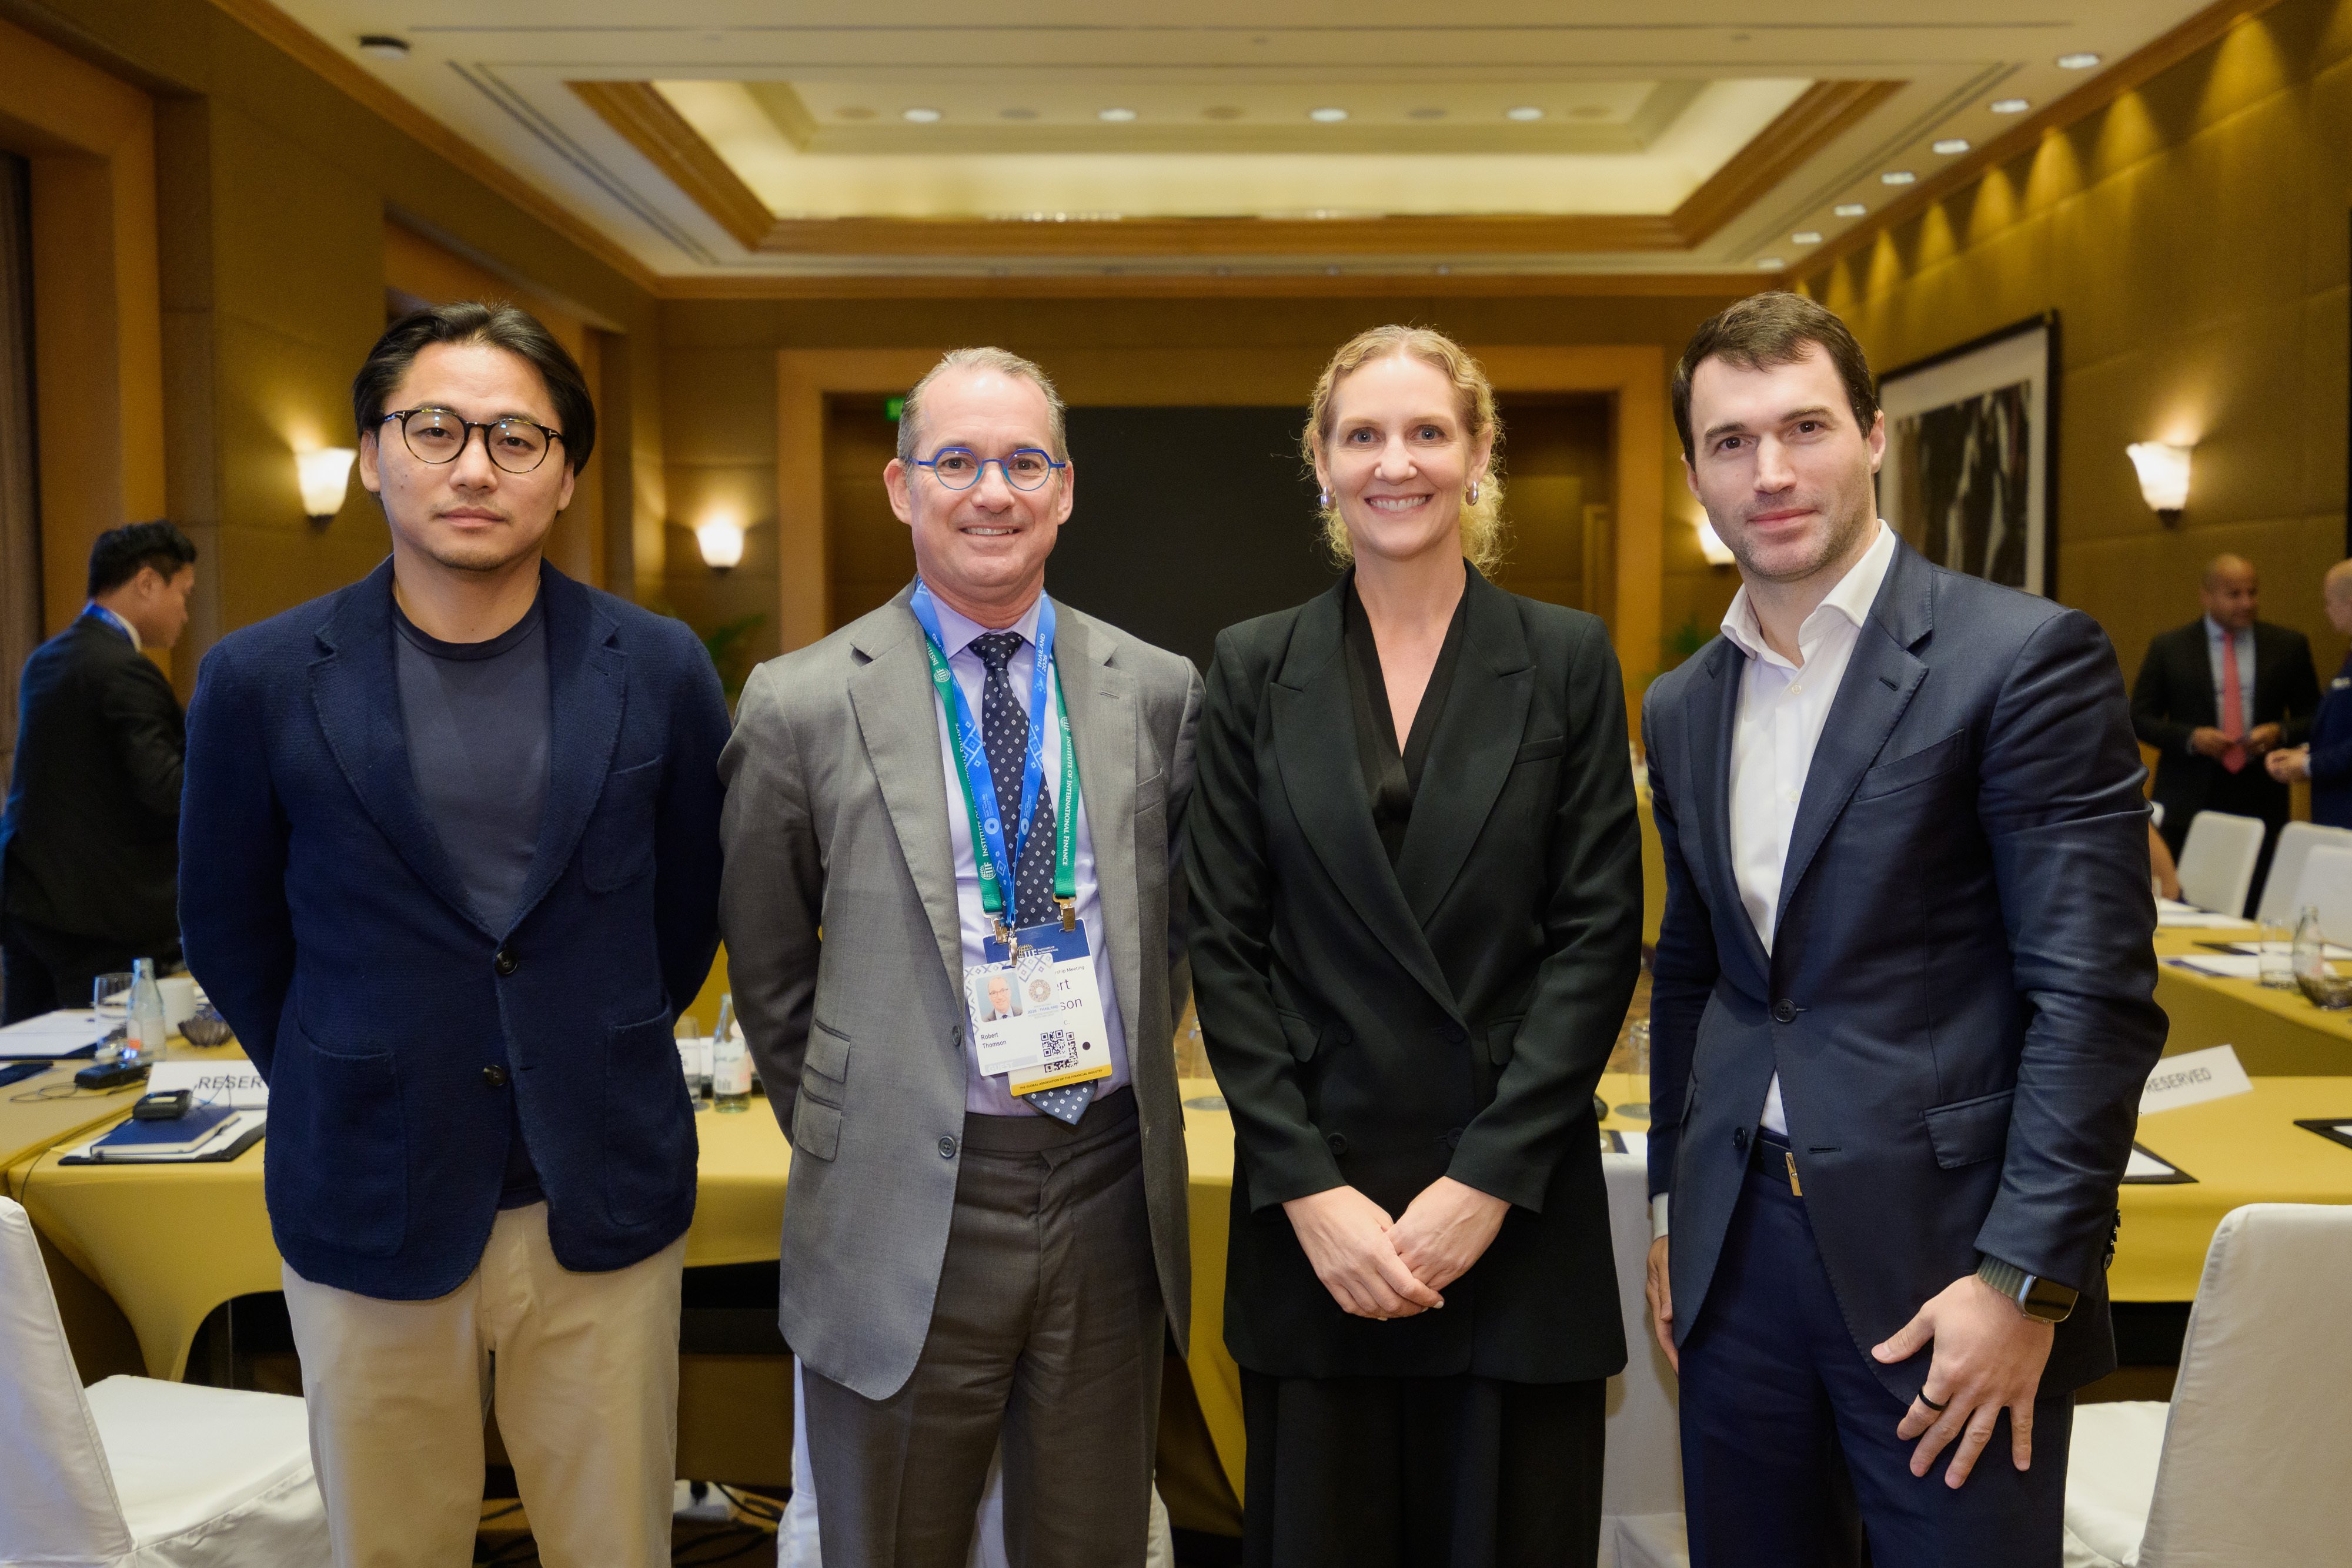
During the Annual Meetings, XTransfer CSO Neil Ni also shared insights at a closed-door panel alongside a Deputy Governor of the Bank of Thailand, contributing XTransfer’s perspective on digital financial safety.
For XTransfer, these discussions centre on a practical priority: enabling businesses to access cross-border financial services while maintaining the controls needed to protect them.
Understanding the Trade Behind the Payment
In his contribution to the World Economic Forum article, Deng emphasised that effective fraud prevention requires more than faster transaction screening. In B2B payments, institutions also need to understand the underlying business and commercial substance of a transaction.[weforum]
“In B2B payments, understanding the underlying business and commercial substance of a transaction can be as important as analyzing the payment itself.”
— Bill Deng, Founder and CEO, XTransfer[weforum]
This makes frontline knowledge and compliance expertise essential. Technology can help identify patterns and improve consistency, but assessing a transaction’s context may require people who understand the customer’s business and can investigate unusual activity.
The objective is not to choose between automation and human review. It is to combine them effectively.
AI Supports Decisions—It Does Not Replace Accountability
As financial institutions increasingly use AI to review transactions, Deng highlighted the continuing importance of experienced human judgement.
AI can improve the speed and consistency of screening. However, some cases still require compliance professionals to assess context, investigate anomalies and respond to emerging fraud patterns. Frontline teams add another layer of understanding by helping establish the commercial purpose behind a payment.[weforum]
For cross-border financial services, the implication is clear: automation should strengthen the control environment, with human expertise available where deeper investigation is needed.
Digital trust depends not only on how quickly a payment can be processed, but also on whether risks can be understood and addressed.
Shared Risk Principles, Locally Calibrated Controls
Asia-Pacific illustrates why effective risk management cannot rely on a single operating model.
The region’s markets differ in regulation, payment infrastructure, customer behaviour and fraud patterns. Deng advocated a shared foundation of risk principles and fraud typology frameworks, while calibrating controls to local conditions.[weforum]
This approach allows institutions to learn from one another without assuming that identical controls will work everywhere. Intelligence identified in one market or payment corridor can serve as an early-warning signal elsewhere as fraud techniques move across borders.
More responsible information sharing can therefore help institutions respond faster while respecting differences in local regulatory and operational requirements.[weforum]
Connecting Payment Infrastructure and Risk Intelligence
Deng also highlighted the fragmentation of SME cross-border payments across banks, payment providers, jurisdictions and risk frameworks.
More connected infrastructure could help combine broader payment reach with richer risk intelligence and more consistent controls. The opportunity is not simply to connect more payment routes, but to improve how institutions understand and manage risk across those routes.[weforum]
This requires cooperation beyond financial services. Fraud can begin on a social platform, an e-commerce marketplace or a telecommunications network before reaching a bank or payment provider. Each participant sees a different part of the activity.
As Deng noted, sustained engagement among financial institutions, payment providers, technology platforms, regulators and law-enforcement authorities is essential to identifying emerging threats earlier and strengthening accountability.[weforum]
Building Trust Where Trade Happens
The Bangkok Blueprint reinforces the importance of a whole-of-ecosystem response to digital financial fraud, including domestic and cross-border cooperation, risk management and consumer protection.[thailand.prd.go][worldbank]
XTransfer’s perspective brings this discussion to the realities of B2B trade: understanding the business behind the transaction, combining technology with professional judgement, and connecting institutions without overlooking local requirements.
For SMEs, access to digital finance and confidence in using it must advance together. XTransfer’s contribution to these discussions underscores the importance of building trust into the infrastructure that supports global trade.
Read Bill Deng’s full contribution in the World Economic Forum article, “Two CEOs discuss how technology can enable financial inclusion while also preventing fraud”.