Cross-Border Payments · Europe-Asia Trade · 2026
How XTransfer and Société Générale Are Streamlining Cross-Border Trade Payments for Global Businesses
1
SME Coverage
897,000+ SMEs globally
Scale
2
Settlement Time
Europe–Asia corridors:The partnership aims to enable faster settlement compared with traditional correspondent banking models.
Speed
3
Payment Visibility
Real-time tracking via API
API
4
Bank–Fintech Model
Combines Société Générale infrastructure + XTransfer platform
Model
+ partnership analysis inside
897,000+ SMEs globally
2-5 business days in traditional correspondent banking models
API real-time tracking and automated workflows
Key Takeaways
→Correspondent banking networks, while essential for international payments, introduce settlement delays of 2–5 business days and create opacity in payment status.
→Direct payment infrastructure connectivity—enabled by bank–fintech partnerships—can reduce settlement times to 1 business day or less for major trade corridors.
→For SMEs engaged in Europe–Asia trade, faster payment settlement directly impacts working capital cycles, supplier relationships, and production planning.
→The Société Générale–XTransfer partnership represents a model of institutional banking infrastructure combined with modern fintech capabilities.
→Enhanced compliance infrastructure and coordinated regulatory frameworks strengthen payment reliability across multiple jurisdictions.
1. Introduction
On June 4, 2026, XTransfer announced a strategic partnership with Société Générale to streamline cross-border payments for global trade transactions. The partnership combines Société Générale's institutional banking infrastructure with XTransfer's modern fintech platform, creating enhanced payment connectivity between Europe and Asia.
This collaboration addresses a persistent challenge in international trade: the inefficiency of correspondent banking networks. For SMEs engaged in Europe–Asia trade, payment delays and limited transparency have long been operational constraints. The partnership aims to reduce these frictions while maintaining regulatory compliance across multiple jurisdictions.
2. The Challenge: Correspondent Banking and Settlement Delays
Correspondent banking is the traditional infrastructure for international payments. When a buyer in Europe sends payment to a supplier in Asia, the payment typically travels through multiple intermediary banks, each applying compliance checks, fees, and processing delays. This network of intermediaries is necessary for regulatory compliance, but it introduces friction into the payment process.
Settlement and visibility impact
Cross-border payments routed through SWIFT and correspondent banking networks often require 2–5 business days, depending on the payment corridor and intermediary banks involved. Research from the Bank for International Settlements has documented a sustained retreat of correspondent banking relationships since the global financial crisis, which has further reduced the number of active cross-border corridors and amplified these settlement delays for SMEs [4]. During this window, payment status visibility is limited, and the buyer and supplier lack real-time confirmation of payment receipt.
For SMEs engaged in Europe–Asia trade, these delays have operational consequences. Suppliers waiting for payment confirmation may allocate production capacity to other buyers who can pay faster. Importers lose visibility into payment status, creating uncertainty about when production will begin. Finance teams must manage multiple payment processes across different banking partners, increasing operational complexity.
Where delays show up
Supplier production capacity decisions
Importer visibility into payment status
Finance-team operational complexity
Typical constraint
Payment status visibility is limited during the settlement window
3. How Bank–Fintech Partnerships Address Payment Inefficiencies
Modern B2B payment platforms address correspondent banking delays by maintaining direct relationships with banking partners in key regions. Rather than routing payments through multiple intermediaries, these platforms enable more direct settlement pathways, reducing processing time from 2–5 days to 1 business day or less.
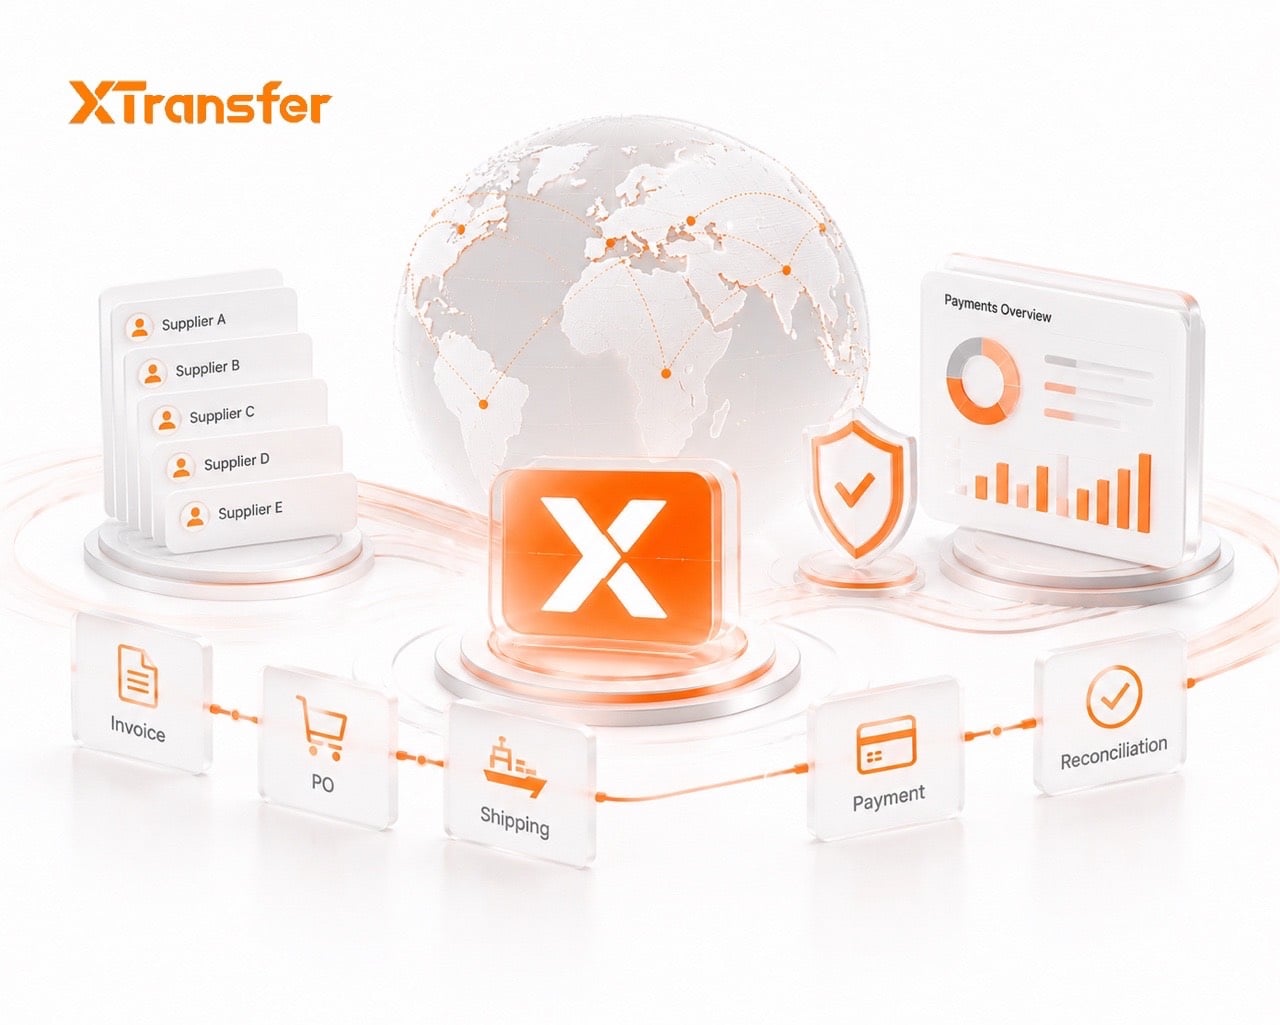
Bank–fintech partnerships combine the institutional infrastructure of traditional banks with the technological capabilities of fintech platforms. Banks provide regulatory relationships, compliance frameworks, and banking network access. Fintech platforms provide API connectivity, real-time payment tracking, and automated workflows.
Key Capabilities
4. The Société Générale–XTransfer Partnership: What It Enables
Société Générale, a major European banking institution, brings institutional infrastructure, regulatory relationships, and access to European banking networks. XTransfer brings fintech capabilities, API infrastructure, and direct relationships with banking partners in key Asian manufacturing regions.
What the collaboration strengthens
The partnership enables XTransfer to offer enhanced payment corridors for Europe–Asia trade, particularly for major currency pairs including USD-CNY related trade flows. The collaboration strengthens both institutions' capabilities: Société Générale gains access to XTransfer's fintech platform and Asian banking network, while XTransfer gains institutional banking infrastructure and European network connectivity.
Illustrative example: An exporter selling goods to overseas buyers may be able to receive payments directly into a local currency account instead of routing funds through multiple conversion steps.Illustrative example only. Actual payment flows depend on participating banks, jurisdictions, and account configurations.
5. Impact on Asia-Europe Trade
Europe and Asia represent two of the world's largest manufacturing and consumption centers. Trade flows between these regions are substantial, but payment infrastructure has not kept pace with the volume and speed of modern supply chains.
Working capital cycles
By enabling faster settlement and enhanced payment visibility, the partnership improves working capital cycles for SMEs engaged in Europe-Asia trade.
Supplier confirmation
Suppliers can confirm payment receipt more quickly, enabling faster production starts.
Importer planning
Importers gain visibility into payment status, reducing uncertainty in supply chain planning.
Corridor variation
Results vary depending on banking partners, local regulations, and payment corridors.
Results vary depending on banking partners, local regulations, and payment corridors. However, for major Europe–Asia trade corridors, the partnership enables settlement times reducing processing time compared with traditional correspondent banking arrangements through more direct payment infrastructure connectivity.
6. Why This Partnership Matters for XTransfer Customers
For XTransfer's 897,000+ SME customers, the partnership with Société Générale represents a significant expansion of payment infrastructure capabilities. The collaboration enables XTransfer to offer enhanced settlement pathways, particularly for Europe–Asia trade corridors where both speed and reliability are critical.
XTransfer customers can now access improved payment visibility, faster settlement for major currency pairs, and more direct connectivity to European banking networks through Société Générale's infrastructure. This is particularly valuable for SMEs that previously faced delays or limited options when sending payments to suppliers in Asia or receiving payments from European buyers.
The partnership also strengthens XTransfer's compliance infrastructure, enabling more efficient handling of cross-border transactions while maintaining regulatory standards across multiple jurisdictions.
Traditional Payment Infrastructure vs Bank–Fintech Collaboration
| Area | Traditional Model | XTransfer + Société Générale |
|---|
| Settlement Path | Multiple intermediaries | More direct infrastructure connectivity |
| Payment Visibility | Limited | Enhanced tracking |
| Local Currency Support | Varies by provider | Expanded capabilities |
| Automation | Manual processes | API-enabled workflows |
| Compliance | Fragmented | Coordinated infrastructure |
7. Conclusion
The Société Générale–XTransfer partnership represents a significant step forward in modernizing payment infrastructure for Europe–Asia trade. By combining institutional banking infrastructure with fintech capabilities, the partnership enables faster settlement, enhanced payment visibility, and more direct connectivity between European and Asian banking networks.
For SMEs engaged in international trade, this partnership translates into tangible operational improvements: faster payment confirmation, reduced working capital delays, and more reliable supplier relationships. As global trade continues to accelerate, payment infrastructure that enables faster, more transparent settlement will become increasingly important for maintaining competitive advantage.
8. Frequently Asked Questions
What does the XTransfer–Société Générale partnership mean for SMEs?
The partnership expands XTransfer's payment infrastructure capabilities, particularly for Europe–Asia trade corridors. SMEs can access faster settlement times, enhanced payment visibility, and more direct connectivity to European banking networks through Société Générale's infrastructure.
How does XTransfer support Europe–Asia trade payments?
XTransfer maintains direct relationships with banking partners in key manufacturing regions and provides same-day or next-day settlement through local payment rails. The Société Générale partnership strengthens this capability by adding European banking network connectivity and enhanced compliance infrastructure.
Why do traditional correspondent banking networks introduce delays?
Correspondent banking routes payments through multiple intermediary banks, each applying compliance checks and processing steps. This network is necessary for regulatory compliance, but it introduces 2–5 day settlement delays. Modern payment infrastructure reduces these delays by enabling more direct settlement pathways.
What is the difference between traditional banking and bank–fintech partnerships?
Traditional banking relies on correspondent networks with multiple intermediaries. Bank–fintech partnerships combine institutional banking infrastructure with modern technology, enabling more direct settlement pathways, real-time payment tracking, and automated workflows.
How does faster payment settlement benefit suppliers?
Suppliers can confirm payment receipt more quickly, enabling faster production starts and improved working capital management. Faster payment confirmation also strengthens supplier relationships by reducing uncertainty about payment status.
What payment corridors does the partnership support?
The partnership particularly strengthens Europe–Asia trade corridors, including USD-CNY. Coverage and settlement times vary depending on banking partners, local regulations, and specific payment corridors.
How does the partnership maintain compliance across multiple jurisdictions?
The partnership combines Société Générale's institutional compliance framework with XTransfer's coordinated infrastructure. This enables efficient handling of cross-border transactions while maintaining regulatory standards across multiple jurisdictions.
Is the partnership available for all payment types?
The partnership particularly benefits B2B trade payments and supplier payments. Availability and settlement times vary by payment corridor and banking partner relationships. Customers should verify specific capabilities with XTransfer for their payment needs.
This article is compiled from publicly available sources and interview content for informational purposes only and does not represent the official views of XTransfer. XTransfer accepts no liability for any damages arising from reliance on this content.